Incorporate a Canadian Subsidiary for Your US Company for $35
We incorporate your Canadian subsidiary for $35, HST included, with government fees shown separately at cost. A CPA settles branch against subsidiary, and your permanent establishment exposure, before we file.
Branch or subsidiary is the first decision. A branch is your US corporation trading in Canada itself, licensed in Ontario under the Extra-Provincial Corporations Act. A subsidiary is a separate Canadian company. We prepare and file a Canadian subsidiary for $35.00, HST included, and pass the registry fee on at cost. Open Corporation for $35 is a department of Gondaliya CPA.
A Chartered Professional Accountant maps your permanent establishment exposure under the Canada-United States tax convention before anything is filed.
Why US Companies Expanding to Canada Incorporate
Canadian buyers and procurement teams want a counterparty with a Canadian business number, a GST/HST number and a Canadian address.
A branch is expensive to run. A non-resident corporation carrying on business in Canada pays Part I tax plus a 25% branch tax under section 219 of the Income Tax Act. Article X(6) of the treaty cuts that to 5% after the first $500,000 of cumulative branch earnings, but the US company itself still files in Canada every year.
A subsidiary replaces that with withholding on dividends, 5% under Article X(2) where the US parent holds at least 10% of the voting stock, and only when a dividend is paid.
Our Official Partners
The Rules That Matter for a US Company in Canada
Expanding into Canada is not a regulated profession, so there is no professional corporation and no limit on who holds shares. Five tax questions decide the structure instead.
| Point | Branch | Canadian subsidiary |
|---|---|---|
| Who files in Canada | The US corporation | The Canadian company |
| Tax on profit taken out | 25% branch tax under section 219, cut to 5% after a $500,000 exemption under Article X(6) | 5% on dividends under Article X(2), at 10% voting ownership |
| When it is charged | On branch earnings, whether or not cash leaves | When a dividend is declared |
| Ontario registration | Extra-provincial licence, $330, with an Ontario agent for service | Articles of Incorporation, $300 |
Already registered here, or need to? See extra-provincial registration and non-residents incorporating in Canada.
Typical Share Structure for a Canadian Subsidiary
| Share class | Who holds it | Voting | Dividend entitlement | Why it is there |
|---|---|---|---|---|
| Class A common | The US parent, ideally a C corporation | Yes | Discretionary | Control, and the 10% voting threshold for the 5% dividend rate |
| Class B common | A Canadian-resident country manager | Yes | Discretionary | A decision maker on the ground |
| Class C preferred | The US parent, for launch capital | No | Fixed | Equity funding instead of loans, which keeps within the thin capitalization rules |
Thin capitalization. Interest paid on loans from the US parent is deductible only while those loans stay within a 1.5 to 1 debt-to-equity ratio under subsection 18(4) of the Income Tax Act. Funding the launch with share capital keeps the interest deductible and avoids the excess being treated as a dividend.
GST/HST for a US Company in Canada
Registration is required once worldwide taxable sales pass $30,000 in a calendar quarter or over four consecutive quarters. Most of what a Canadian subsidiary sells here is taxable, at 13% in Ontario. Our GST/HST registration guide sets out the timing.
Common CRA Issues for US-Owned Companies
Regulation 105 under-withholding
Paying the parent’s invoice in full for engineers or consultants who worked in Canada. The CRA assesses the Canadian payer.
An accidental permanent establishment
A US employee habitually concluding contracts in Canada, or service visits crossing the Article V(9) threshold.
Transfer pricing without documentation
A round-number monthly management fee to the parent with no analysis behind it.
Part XIII under-withholding
Paying royalties, licence fees or certain other amounts to the parent with no withholding and no treaty-benefit form on file. Without the form, the 25% statutory rate applies.
First-Year Compliance Calendar
| When | What is due | Who files it | What happens if it is late |
|---|---|---|---|
| Day one | Articles of Incorporation | Us, in the Ontario Business Registry | No Canadian entity to contract with |
| Within 60 days of incorporation | Initial Return under the Corporations Information Act, no fee | Us, in the Ontario Business Registry | Non-compliance under that Act |
| Before the first invoice | Business number and RC0001 corporate tax account | Your CPA | Nothing to file the T2 against |
| Day one, or before $30,000 | GST/HST registration | Your CPA | Tax assessed on past sales, plus interest |
| Before paying the parent for services in Canada | Regulation 105 withholding, or a waiver | The Canadian payer | The CRA assesses the payer |
| 15th of the following month | Payroll source deductions and Part XIII withholding | The corporation | Penalties, and director liability under section 227.1 |
| Within 53 weeks of incorporation | First fiscal year end chosen | The directors | Changing it later needs CRA approval |
| 2 months after year end | Corporate tax balance | The corporation | Interest at the prescribed rate |
| 6 months after year end | T2 return, T106 where required, and the Ontario Annual Return | Your CPA, and us | Late filing penalties |
First: does your US company already have a permanent establishment in Canada?
Existing exposure
Site visits, a home-office salesperson or an installation contract may already have created a permanent establishment.
Branch against subsidiary, in numbers
Early Canadian losses usable against US income point one way, repatriating profit the other. Both go on one page.
The parent entity
An LLC parent is raised early, because a transparent entity does not get the treaty position a C corporation has.
Jurisdiction and board
Ontario has no director residency rule. A federal corporation needs 25% resident Canadians, who carry director liability for payroll and GST/HST.
Funding and pricing
Share capital against loans within the 1.5 to 1 ratio, intercompany charges set and documented in year one, GST/HST registration and payroll before the first hire.
AFFORDABLE Incorporation Pricing for US Companies
Our fee is $35.00 with HST included. Every government fee is its own line, at the amount the government charges.
| Item | Amount | HST | Total | Who charges it |
|---|---|---|---|---|
| Incorporation preparation and filing | $35.00 | Included | $35.00 | Open Corporation for $35 |
| Ontario Articles of Incorporation, filed online | $300.00 | Not applicable | $300.00 | Ontario Business Registry |
| Federal Articles of Incorporation, filed online, if you choose federal | $200.00 | Not applicable | $200.00 | Corporations Canada |
| Ontario NUANS name search report, named company only | $25.00 | Included | $25.00 | Ordered through us |
| Ontario extra-provincial licence, if you choose a branch | $330.00 | Not applicable | $330.00 | Ontario Business Registry |
| Minute book, GST/HST, T2 and transfer pricing | Quoted on request | Included in the quote | Quoted on request | Gondaliya CPA |
A numbered company needs no NUANS report. A subsidiary that shares its parent’s brand usually takes a named company.
Our Services for US Companies
Our professional fees include HST. Government fees are separate, itemised and charged at cost with no mark-up.
Incorporation Services for US Companies
Incorporate in Canada for just $35, HST included, with a CPA review before filing.
NUANS Name Search and Report for US Companies ($25)
A $25 NUANS report, checked by a CPA before you incorporate.
Address Service for US Companies ($75)
A registered office address that keeps your home address private.
Annual Return Filing for US Companies
Federal and Ontario annual returns filed on time to keep your corporation active.
Corporate Tax Filing for US Companies (From $300)
Your T2 corporate tax return, prepared by a CPA, from $300.
Payroll Service for US Companies
Payroll and CRA source deductions for owners and staff.
Incorporate in Ontario
Ontario incorporation for $35 plus the $300 government fee, often processed the same day.
Federal Incorporation
Federal incorporation for $35 plus the $200 government fee, with your name protected across Canada.
Holding Company Setup for US Companies
A holding company for $35, structured by a CPA for tax-efficient dividends.
The Bundle for US Companies Expanding to Canada
After the certificate is issued, Gondaliya CPA takes over the cross-border work: the Canadian T2 and Ontario filings, GST/HST returns, payroll and T4 slips, the Regulation 105 position on payments to the parent, the transfer pricing file, the T106, and Part XIII withholding with NR4 reporting.
Why US Companies Use Us
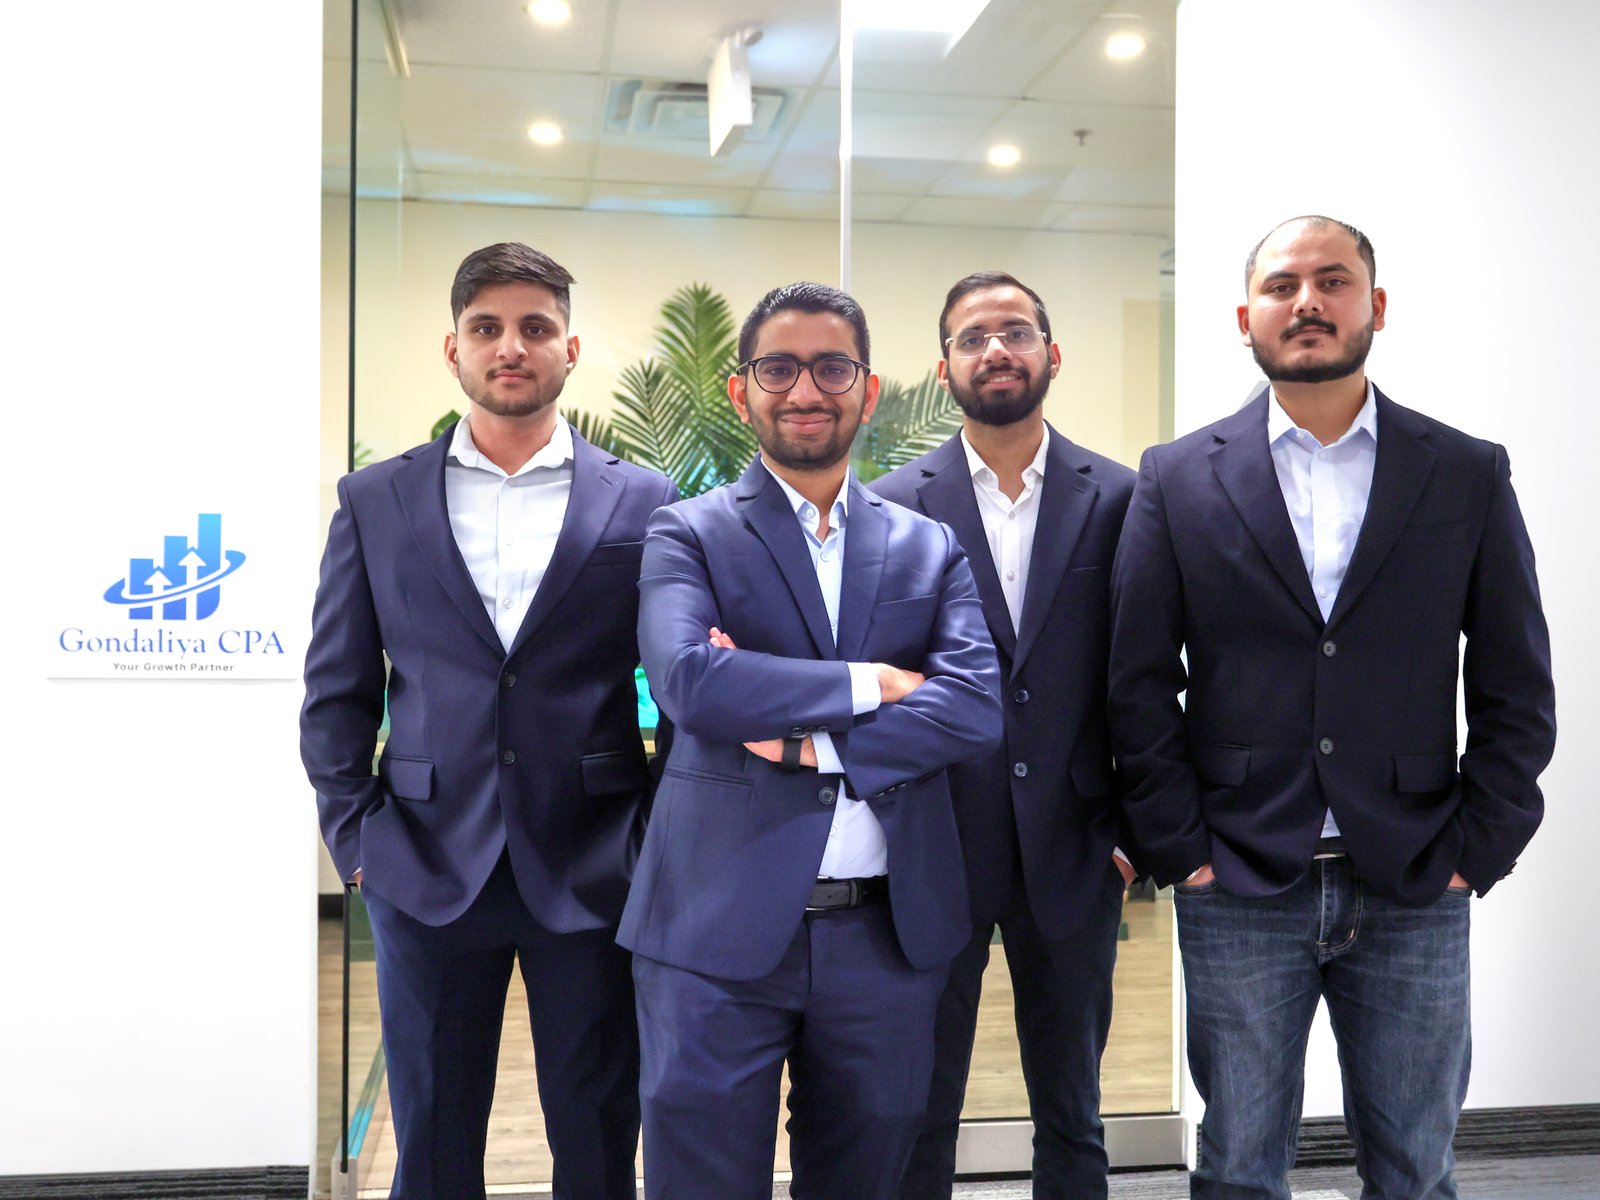
Gondaliya CPA Professional Corporation is registered with CPA Ontario under firm registration number 61330051. Our clients have left us 1,300+ five-star Google reviews, and we work from 13 Ontario offices, open 9:00 AM to 8:30 PM, Monday to Sunday. We back every filing with a 30-day money-back guarantee and a 60-day fee-matching policy, and we are a Xero Partner Award Winner 2026. Open Corporation for $35 is a department of Gondaliya CPA.
- CPA Ontario firm registration number 61330051
- 1,300+ five-star Google reviews
- 13 Ontario offices
- Open 9:00 AM to 8:30 PM, Monday to Sunday
- 30-day money-back guarantee
- 60-day fee-matching policy
- Xero Partner Award Winner 2026
Google Reviews
Free CPA Consultation for US Companies Expanding to Canada
Case Studies: US Companies Expanding to Canada
Three cross-border files, each showing where the company started and what changed before anything was filed.
Software Company – A Salesperson in Toronto
The problem: A US software company had a salesperson working from home in Toronto and signing customer contracts.
What we did: We flagged the permanent establishment risk, incorporated an Ontario subsidiary to employ the salesperson, and set an arm’s length service fee with the parent.
The result:
- Exposure contained
- Canadian payroll in place
- Intercompany fee documented
Equipment Maker – Installation Crews
The problem: A US manufacturer was sending crews to install equipment for Canadian customers and invoicing from the US.
What we did: We set up Regulation 105 waivers for the crew visits, then incorporated a subsidiary once Canadian work became regular.
The result:
- Withholding handled
- Subsidiary for ongoing work
- GST/HST registered from day one
LLC Parent – Treaty Question
The problem: A US LLC wanted to own a new Canadian company directly.
What we did: We explained the treaty problem with LLC ownership, and the owners formed a US C corporation to hold the Canadian shares.
The result:
- Clean treaty position
- 5% dividend rate available
- Board of US officers
Six steps from the intake form to a Canadian company ready to trade.
Send the intake form
The US parent, its entity type, the planned Canadian activity and who will sit on the board.
A CPA reviews the file
Permanent establishment exposure, branch against subsidiary, funding and GST/HST.
The name
A numbered company needs no search. A named company is checked with a $25.00 NUANS report.
You approve the draft
You see the articles, the share classes and the registered office before anything is filed.
Filed online
The articles go through the Ontario Business Registry at $300.00, and you receive the certificate of incorporation.
Accounts
Business number, GST/HST and payroll accounts, ready for the first Canadian customer or hire.
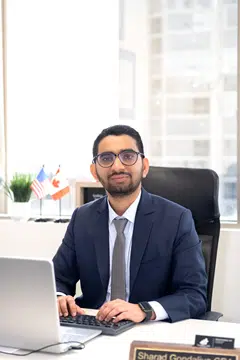
Meet the Lead CPAs Behind Your Canadian Subsidiary
A Chartered Professional Accountant checks the treaty position and the structure before anything is filed.
What Our Clients Say
These Google reviews belong to Gondaliya CPA Professional Corporation and cover every service the firm provides. See all reviews.
Incorporating a Canadian Subsidiary Anywhere in Canada
We incorporate Canadian subsidiaries for US companies from thirteen Ontario offices, and the filing is electronic, so no one needs to travel. See also incorporating by province and import and export businesses.
Canadian Subsidiary FAQs
Should a US company open a branch or a Canadian subsidiary?
What is the branch profits tax exemption?
When does a US company have a permanent establishment in Canada?
What is Regulation 105 withholding?
Can a US LLC own the Canadian company?
Does the Canadian subsidiary have to register for GST/HST?
What tax rate does a US-owned Canadian company pay?
What transfer pricing documentation does Canada require?
Related Pages
Non-Residents Incorporating in Canada
- Director residency
- Part XIII
- Thin capitalization
Import and Export
- Customs accounts
- Zero-rated exports
- Import GST
Extra-Provincial Registration
- Branch licence
- Agent for service
- Fees by province
IT Consultants
- US clients
- Services abroad
- HST on fees
Read our Ontario incorporation service and the federal incorporation service for the wider rules.
Settle Branch or Subsidiary First
Branch or subsidiary is expensive to reverse. Complete the intake form, pay $35 including HST, and a Chartered Professional Accountant settles the structure before anything is filed.
No legal advice. Gondaliya CPA Professional Corporation is a firm of Chartered Professional Accountants licensed by CPA Ontario, firm registration number 61330051. It is not a law firm. We prepare and file corporate documents and we provide accounting and tax advice. Nothing on this page is legal advice, and reading it creates no solicitor and client relationship. For legal advice, including advice on a shareholder agreement before you sign it, consult a lawyer licensed in the province where your corporation carries on business.
Open Corporation for $35 is a department of Gondaliya CPA.